50/30/20 Budgeting: How to Cut Expenses Without Sacrificing Lifestyle
A rigorous mathematical guide to determining your target retirement nest egg, understanding the 4% rule, modeling safe withdrawal rates (SWR), and hedging sequence of returns risk.
Sarah Jenkins, CFP®Senior Wealth Strategist
Published: August 31, 2026•Updated: August 31, 2026
Strategic retirement calculations model inflation, portfolio longevity, and safe withdrawal distributions.
💡
Key Takeaways & Quick Rules
The 25x Rule (4% SWR): Multiply your estimated annual retirement expenses by 25 to find your baseline nest egg (e.g., $60,000/yr requires $1.5M).
Retirement Horizon Adjustments: Early retirees (FIRE timeline: 40+ years) should model a conservative 3.25% to 3.5% withdrawal rate (28x–30x expenses).
Sequence of Returns Risk (SRR): Market downturns in the first 5 years of retirement can prematurely deplete capital without a 2–3 year cash buffer.
Inflation Guard: Annual withdrawals must adjust for Consumer Price Index (CPI) increases to preserve real purchasing power.
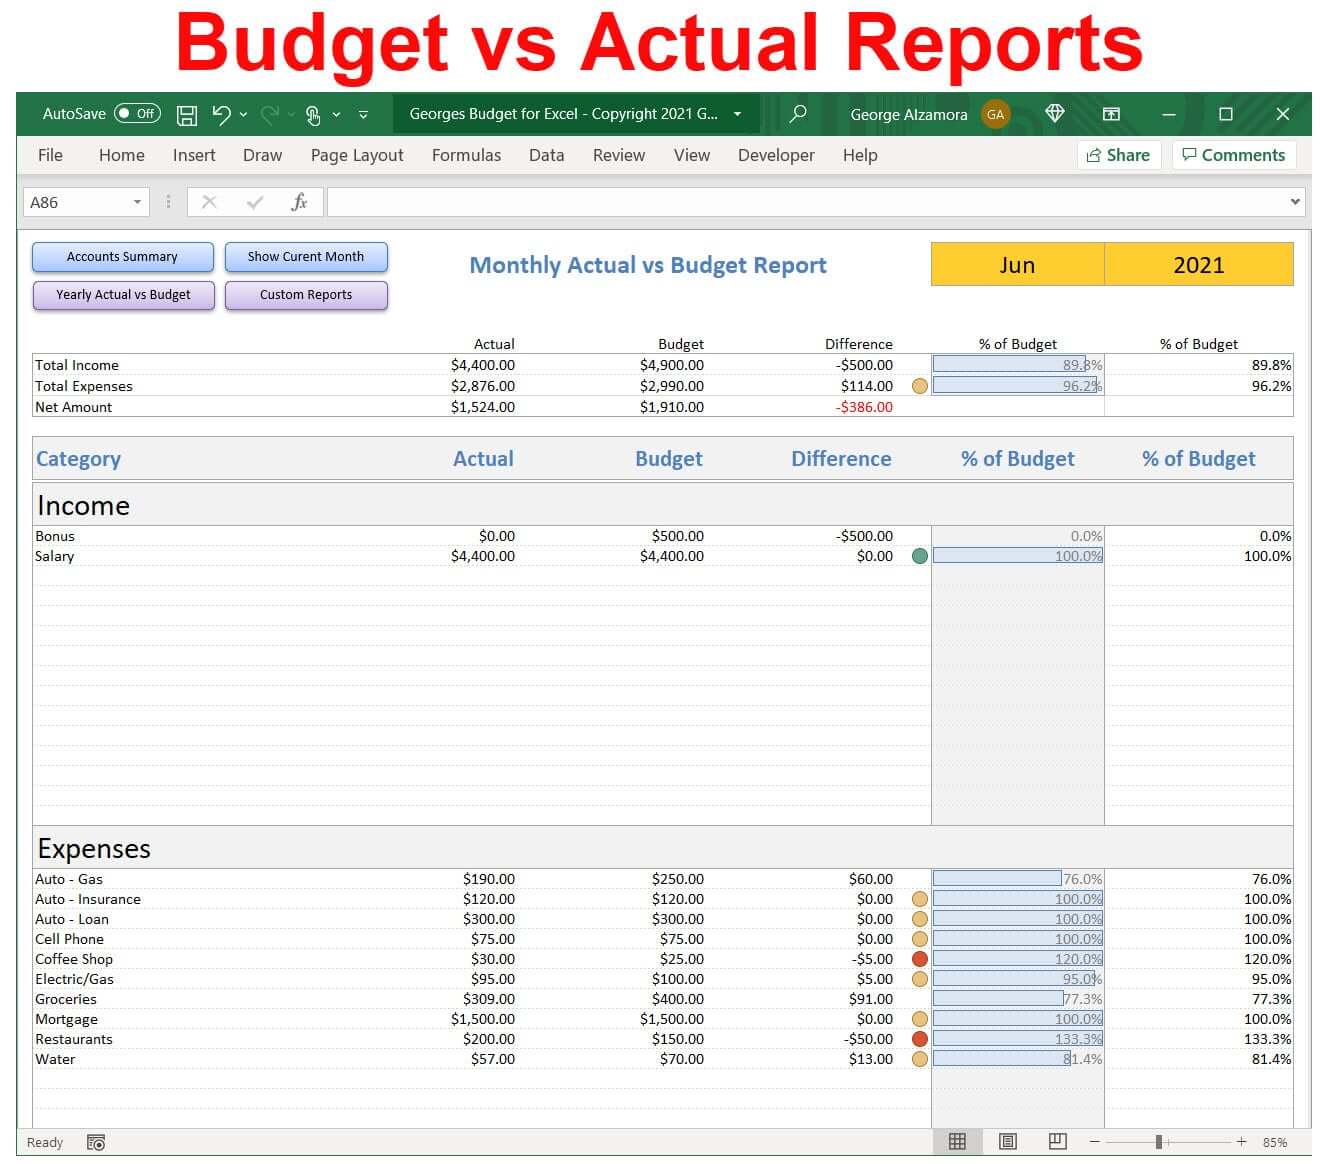
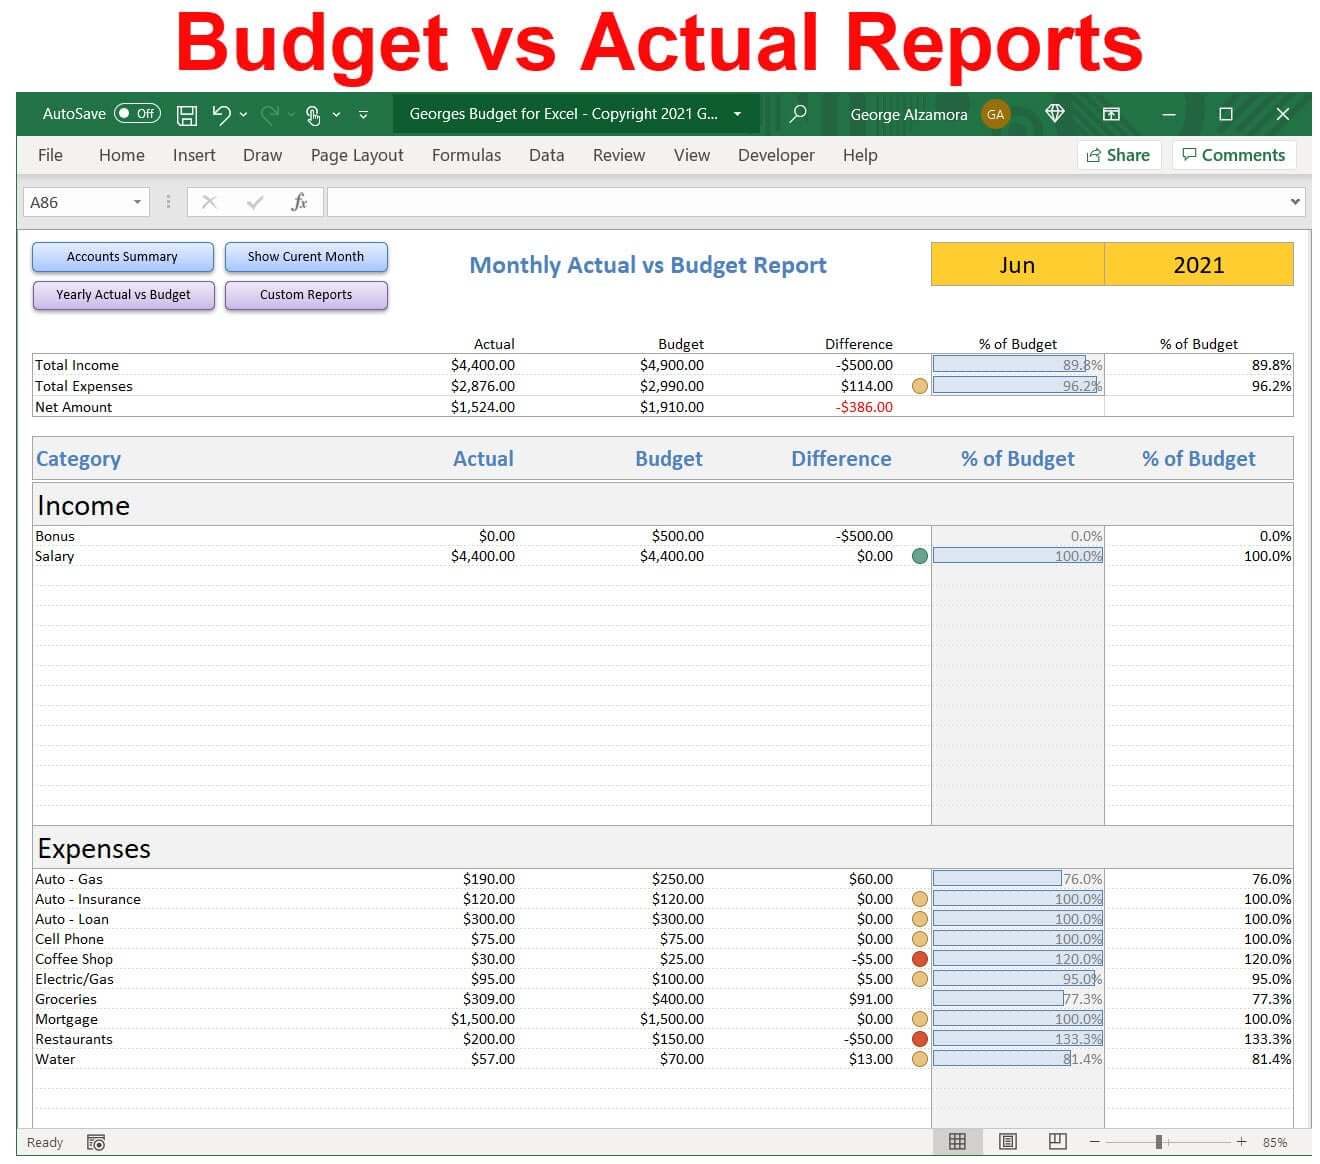
Conscious spending is not about deprivation—it is about intentionality. By organizing your monthly cash flow into 50% Needs, 30% Wants, and 20% Savings, you build a sustainable spending framework.
Eliminating Hidden Subscriptions
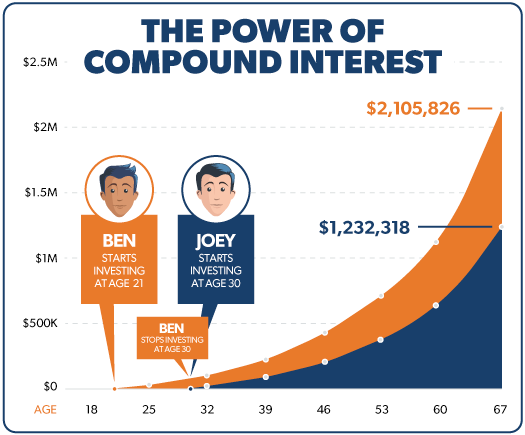
Audit recurring monthly charges and high banking fees. Redirecting even $200 a month into low-cost index funds can yield hundreds of thousands in retirement.
Sarah is a Certified Financial Planner with over 14 years of wealth advisory experience specializing in portfolio architecture, tax-advantaged asset location, and early retirement modeling. Her research has been featured in top personal finance publications.